Whenever international bond yields climb, the conventional perspective characterizes it as negative for bitcoin BTC$84,490.60. Yet throughout most of BTC’s existence, the cryptocurrency has demonstrated minimal to zero steady correlation with bonds.
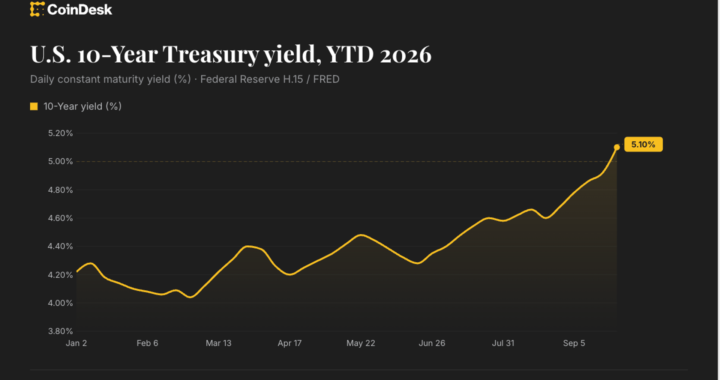
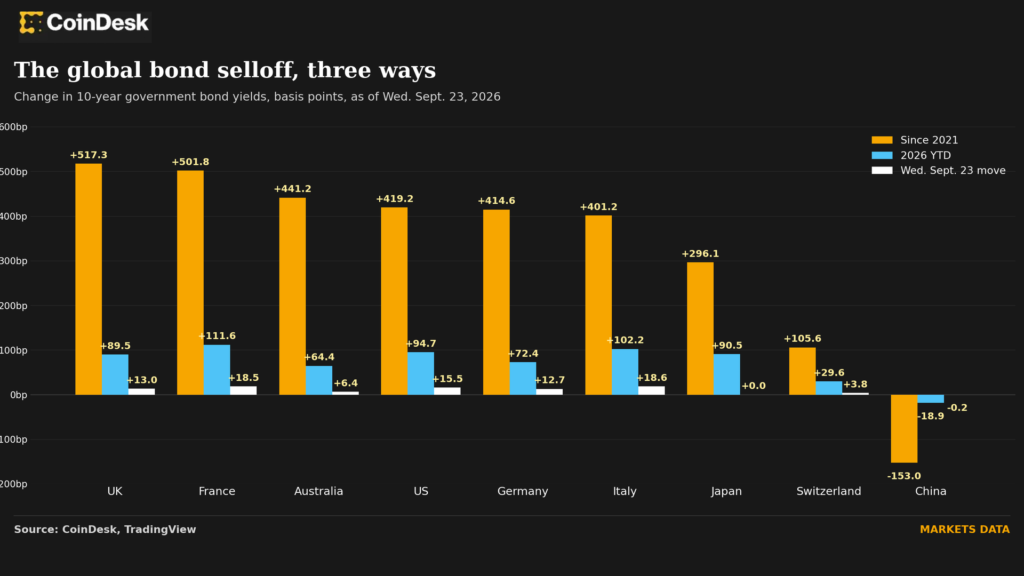
Yields returned sharply to the spotlight on Wednesday. The American 10-year note climbed 15 basis points to reach its peak mark since 2007, pushing past 5.13%, and dragged yields higher internationally, as the visual illustration indicates.
The standard viewpoint dictates that as yields expand, the opportunity expense of retaining non-interest-paying assets like bitcoin and gold increases, potentially shifting capital toward bonds instead. In summary, it presents a headwind rather than a tailwind for the crypto sector.
Such rationale sounds logical theoretically. However, statistical correlations do not support it.
The 90-day correlation linking bitcoin’s day-to-day returns and the daily movements of the U.S. 10-year yield sits at merely −0.18, according to metrics evaluated by CoinDesk. This reading remains close to zero and is virtually indistinguishable from a complete lack of relationship.
Extended timeframes illustrate identical patterns, with the 180-day correlation standing at −0.06 and the 1-year metric resting at −0.03. Bitcoin remains equally disconnected from the yields of other nations.
Maintaining such an uncorrelated status serves as a distinct advantage. It implies that bitcoin can fulfill a function comparable to other alternative investments by enhancing a portfolio’s risk-adjusted returns, a concept investment banks have contended for years. Cryptocurrency researchers propose the identical perspective.
"Bitcoin’s near-zero correlation with U.S. Treasury yields is a genuine portfolio advantage because it suggests BTC is not simply trading as a duration or rates asset. Recent data shows the 90-day correlation between Bitcoin’s daily returns and the U.S. 10-year yield at around -0.17, with the relationship at times moving even closer to zero," stated Lacie Zhang, research lead at Bitget Wallet, in an interview with CoinDesk.
Bitcoin’s broader trajectory corroborates this dynamic as well. It has advanced 191% since 2021 and achieved a record valuation of $126,000 last October. This occurred even while 10-year yields advanced more than 500 basis points within the U.K. and France, and surpassed 400 across the U.S., Australia, Germany, and Italy over that identical timeframe.
Japanese and Swiss yields have advanced by 296 and 105 basis points, respectively, whereas Chinese yields have declined as the nation has been combating deflation.
Focus on bond volatility
Remaining broadly uncorrelated does not automatically shield bitcoin from near-term distress, particularly when that distress stems from bond market instability itself rather than the absolute level of yields.
An abrupt surge in bond market turbulence, particularly within Treasuries which anchor global finance, can constrain financial conditions, elevate borrowing costs, and provoke widespread risk aversion.
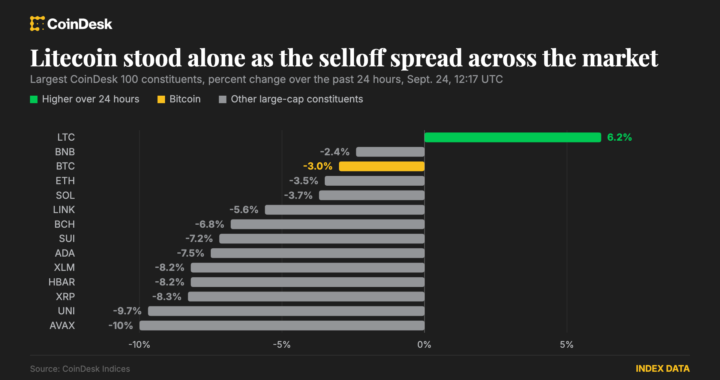
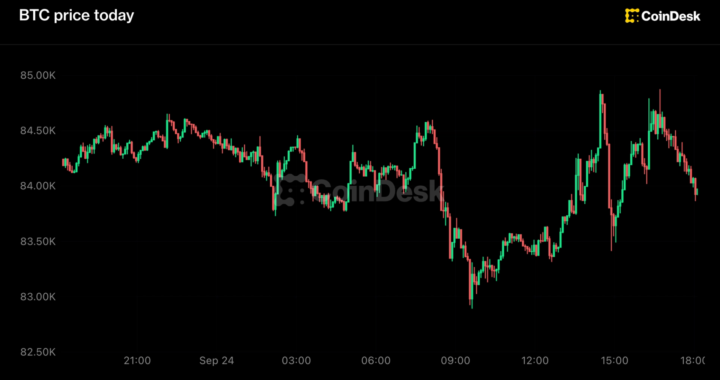
The MOVE Index, which measures anticipated instability in Treasury notes, jumped 21% to reach 95 points on Wednesday, marking its loftiest level since April 1. This dynamic helps account for bitcoin’s retreat from $87,200 down to $83,500 on Wednesday, though the marketplace might also have simply sought a justification to correct following its recent aggressive upward surge.
Should Treasury turbulence persist or climb higher, bitcoin could experience deeper corrections.
Yields rise
The upward movement in yields on Wednesday was spearheaded by U.S. economic reports rather than fiscal anxiety.
S&P Global’s preliminary U.S. Composite PMI climbed to 58.4 in September, marking its highest reading since July 2021, shifting upward from 56.0 in August, with corporate activity scaling at its quickest pace in over five years alongside mounting inflationary pressures.
That report reinforced projections that the Federal Reserve will be forced to maintain rate hikes following the September interest rate increase of 25 basis points. Both the 10-year and two-year yields surged in response.
Nevertheless, a closer examination of the featured graphic demonstrates that French yields actually climbed higher than American yields on Wednesday, despite U.S. economic metrics triggering the shift. British yields also advanced nearly as much as those in the U.S. According to Robin Brooks, Senior Fellow at the Brookings Institution and former chief economist at the IIF, the exact trend applied to Italy and Greece.
"What happened today is that we got strong data for the U.S. and then fiscally vulnerable places caught on fire," Brooks noted in a Substack publication released on Wednesday.
This phenomenon is not unprecedented, according to Brooks. Financial markets have been penalizing nations carrying heavy fiscal debt loads for some time now.
Japan held the leading position at the close of 2025 with a debt-to-GDP ratio exceeding 200%, followed by the U.S. at 123.8%, based on figures from Statista. France and the U.K. recorded figures at 115% and 102%, respectively, trailed by China at 100%.
Meanwhile, Switzerland’s federal debt amounted to merely 16% of its gross domestic product, representing a bright spot. This dynamic, combined with a more controlled increase in its 10-year bond yield over recent years, has prompted certain analysts to label the Swiss franc (CHF) as a safe haven that is steadily supplanting the Japanese yen as the preferred carry currency.
For bitcoin, the narrative remains straightforward. The pressures unsettling bond markets—including fiscal credibility, growth trajectories, and inflation across Paris, London, or New York—are being incorporated into yields and impacting fiat currencies, yet they have failed to materialize in bitcoin’s historical price performance over the years.
Originally published at https://www.coindesk.com/markets/2026/09/24/the-data-proves-it-bitcoin-doesn-t-care-about-rising-bond-yields-over-long-term.