American decision-makers could drive up cryptocurrency valuations by expanding the money supply to fund artificial intelligence and cover public debt, according to Maelstrom fund chief investment officer Arthur Hayes.
Artificial intelligence businesses require trillions of dollars to build out data centers even as service fees decline, Hayes explained during a discussion at the CONNECT by Cointelegraph: Seoul Edition event on Tuesday at Korea Blockchain Week.
“They’ve not really given themselves a lot of options other than print money and make it less bad,” he noted.
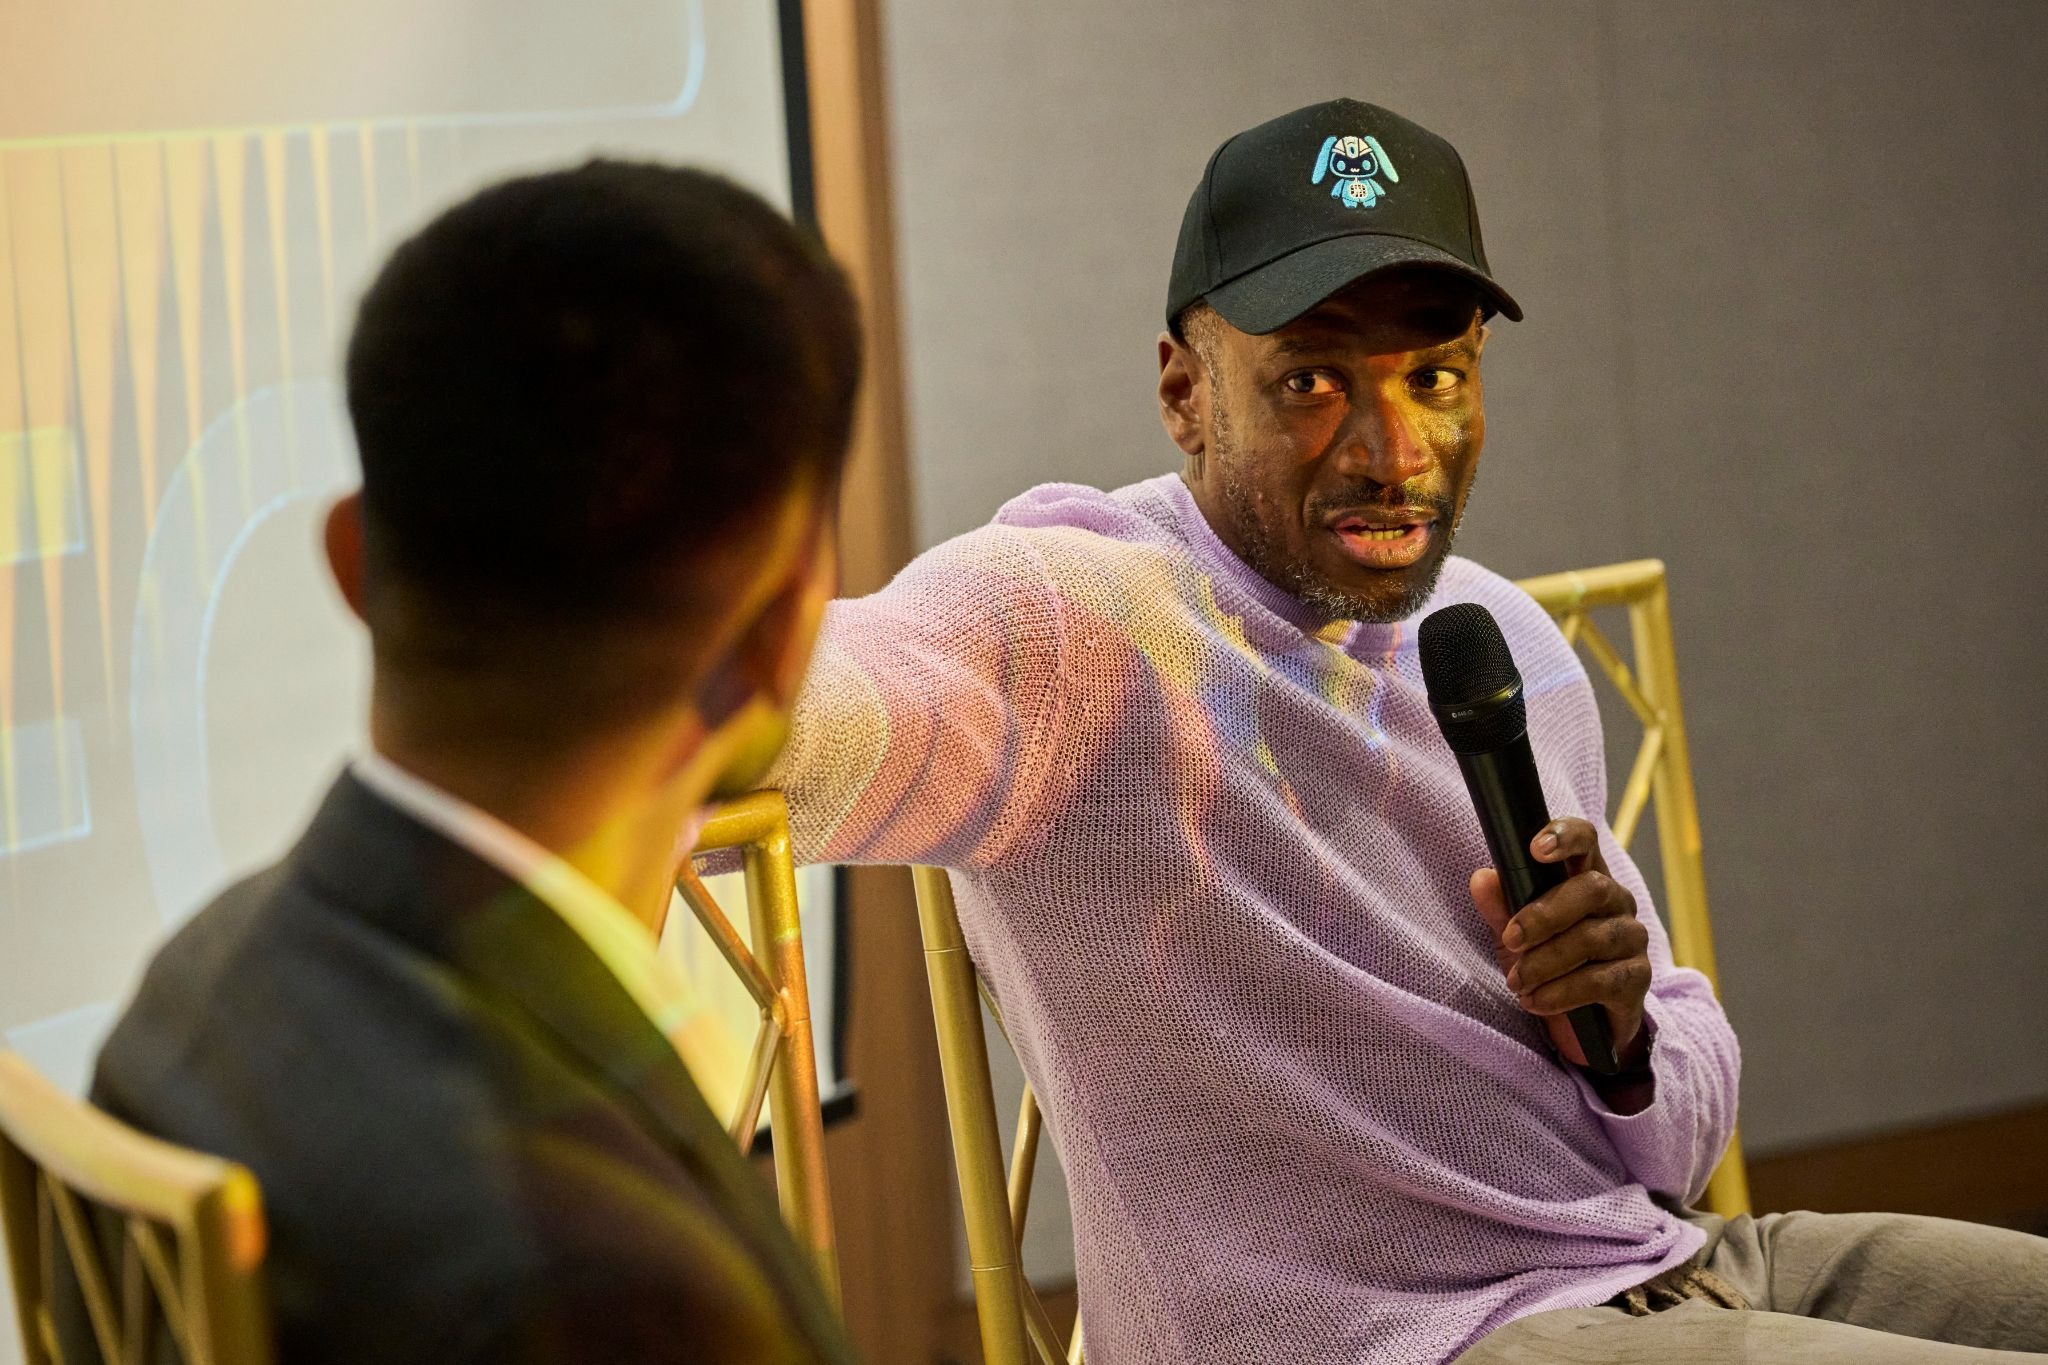
Hayes additionally touched upon a potential transition in China away from a so-called “austerity lite” strategy toward significant monetary easing, which he stated could stimulate demand for finite resources.
Related: AI credit bubble could fuel Bitcoin ‘crack-up boom’ past $1M: Hayes
Within Europe, he mentioned he was keeping an eye on fiscal pressure in France, specifically credit-default swaps connected to BNP Paribas alongside French sovereign bond yield gaps.
I think the money printing will essentially happen at some point, but that’s sort of a slow motion train wreck happening underneath the surface.”
The CONNECT conference hosted by Cointelegraph in Seoul included discussion panels spanning traditional finance’s migration onchain, stablecoins, and corporate crypto reserves.
Wall Street’s move onchain leaves room for middlemen
Financial institutions and asset managers bring an established consumer base to distributed ledger markets, granting them an edge over entities that must build investor interest entirely from the ground up, observed Portal Ventures general partner Catrina Wang.
“Whoever owns the customer relationship owns the economics,” Wang remarked, referencing technology analyst Ben Thompson’s aggregation theory.
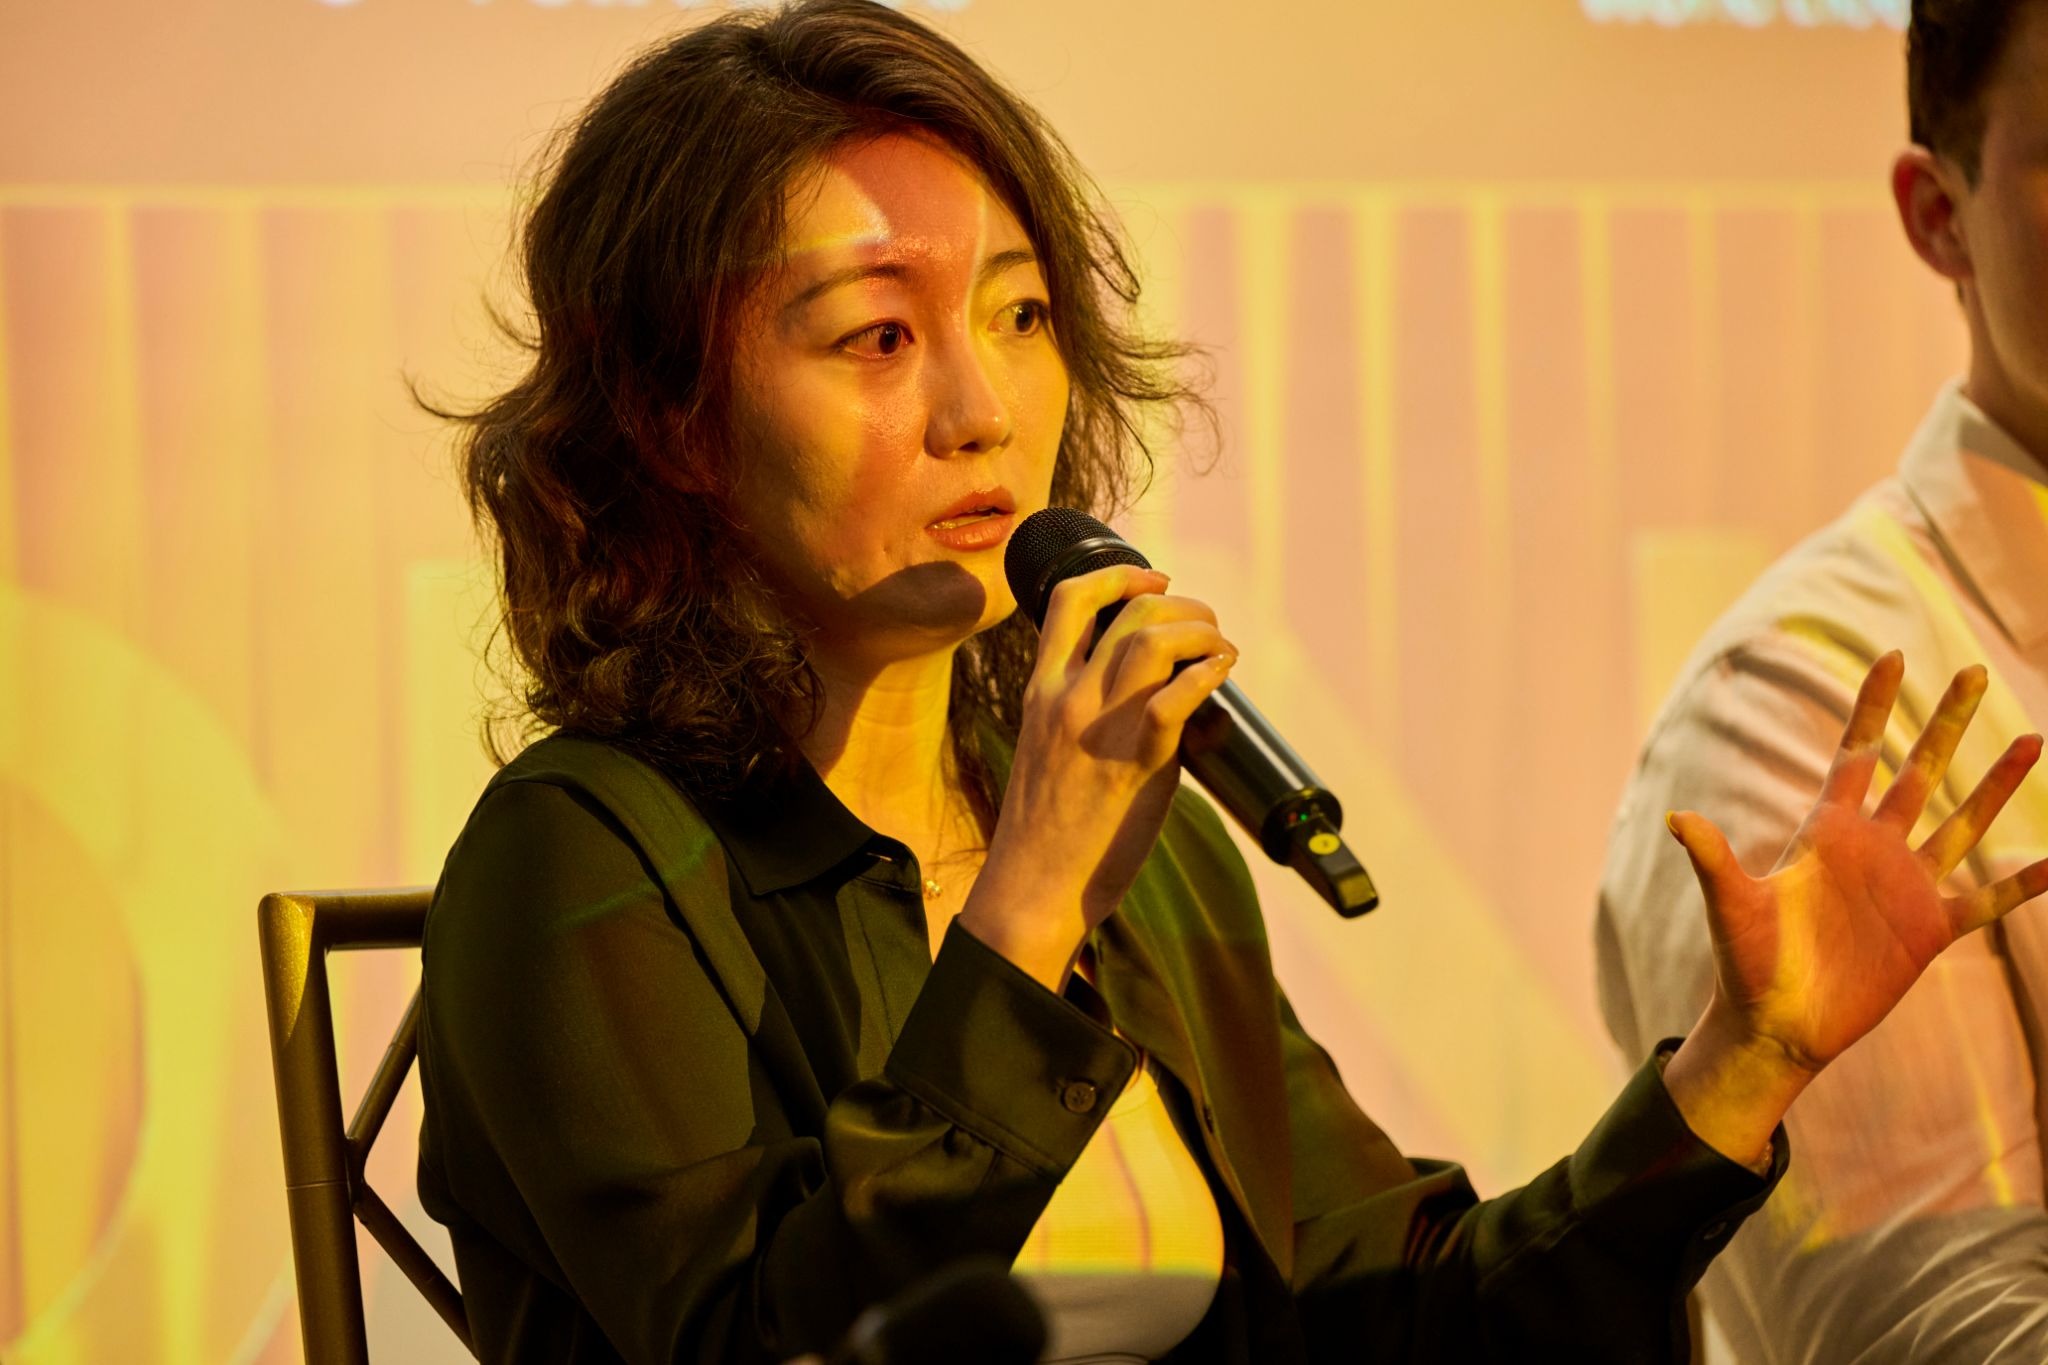
Catering to current patrons represents only part of the opportunity for banking entities. R3 co-founder Todd McDonald pointed out that permissionless blockchains likewise grant entry to clientele outside proprietary institutional networks.
R3 initially established its operations around closed financial networks utilizing its Corda framework, prior to revealing a partnership in May 2025 aimed at linking institutions and their capital to Solana’s open ledger.
You need to really go to where the customers are and where they will be in the future.”
Once investors gain entry to those venues, they must still determine capital allocation and risk thresholds.
World Liberty Financial executive vice president of growth Justin Kugel pointed out that such choices continue to generate demand for intermediaries, contrasting with the cryptocurrency sector’s original objective to remove middlemen entirely.
“Maybe there’s a reason why there are so many middlemen in TradFi,” Kugel stated.
Numerous participants prefer not to oversee their holdings independently or evaluate every financial risk, favoring the reassurance provided by centralized trading platforms instead, according to Kugel.
Stablecoins move money, but who supplies the yield?
Franklin Templeton currently holds no intentions of releasing a proprietary stablecoin, preferring instead to have its tokenized money market products supply investment returns alongside transactional assets, explained Chetan Karkhanis, senior vice president of digital asset client relations at the company.
“Let us be the yield layer,” Karkhanis said.
Subscriptions and payouts for Franklin Templeton portfolios typically still necessitate standard fiat money, Karkhanis explained. Certain conversion mechanisms involving stablecoins already exist, though he emphasized those alternatives must see broader adoption across the wider sector.
Franklin Templeton entered into a collaboration with MoonPay back in June permitting qualified institutional clients to transition between supported stablecoins and its tokenized money market assets via onchain operations.
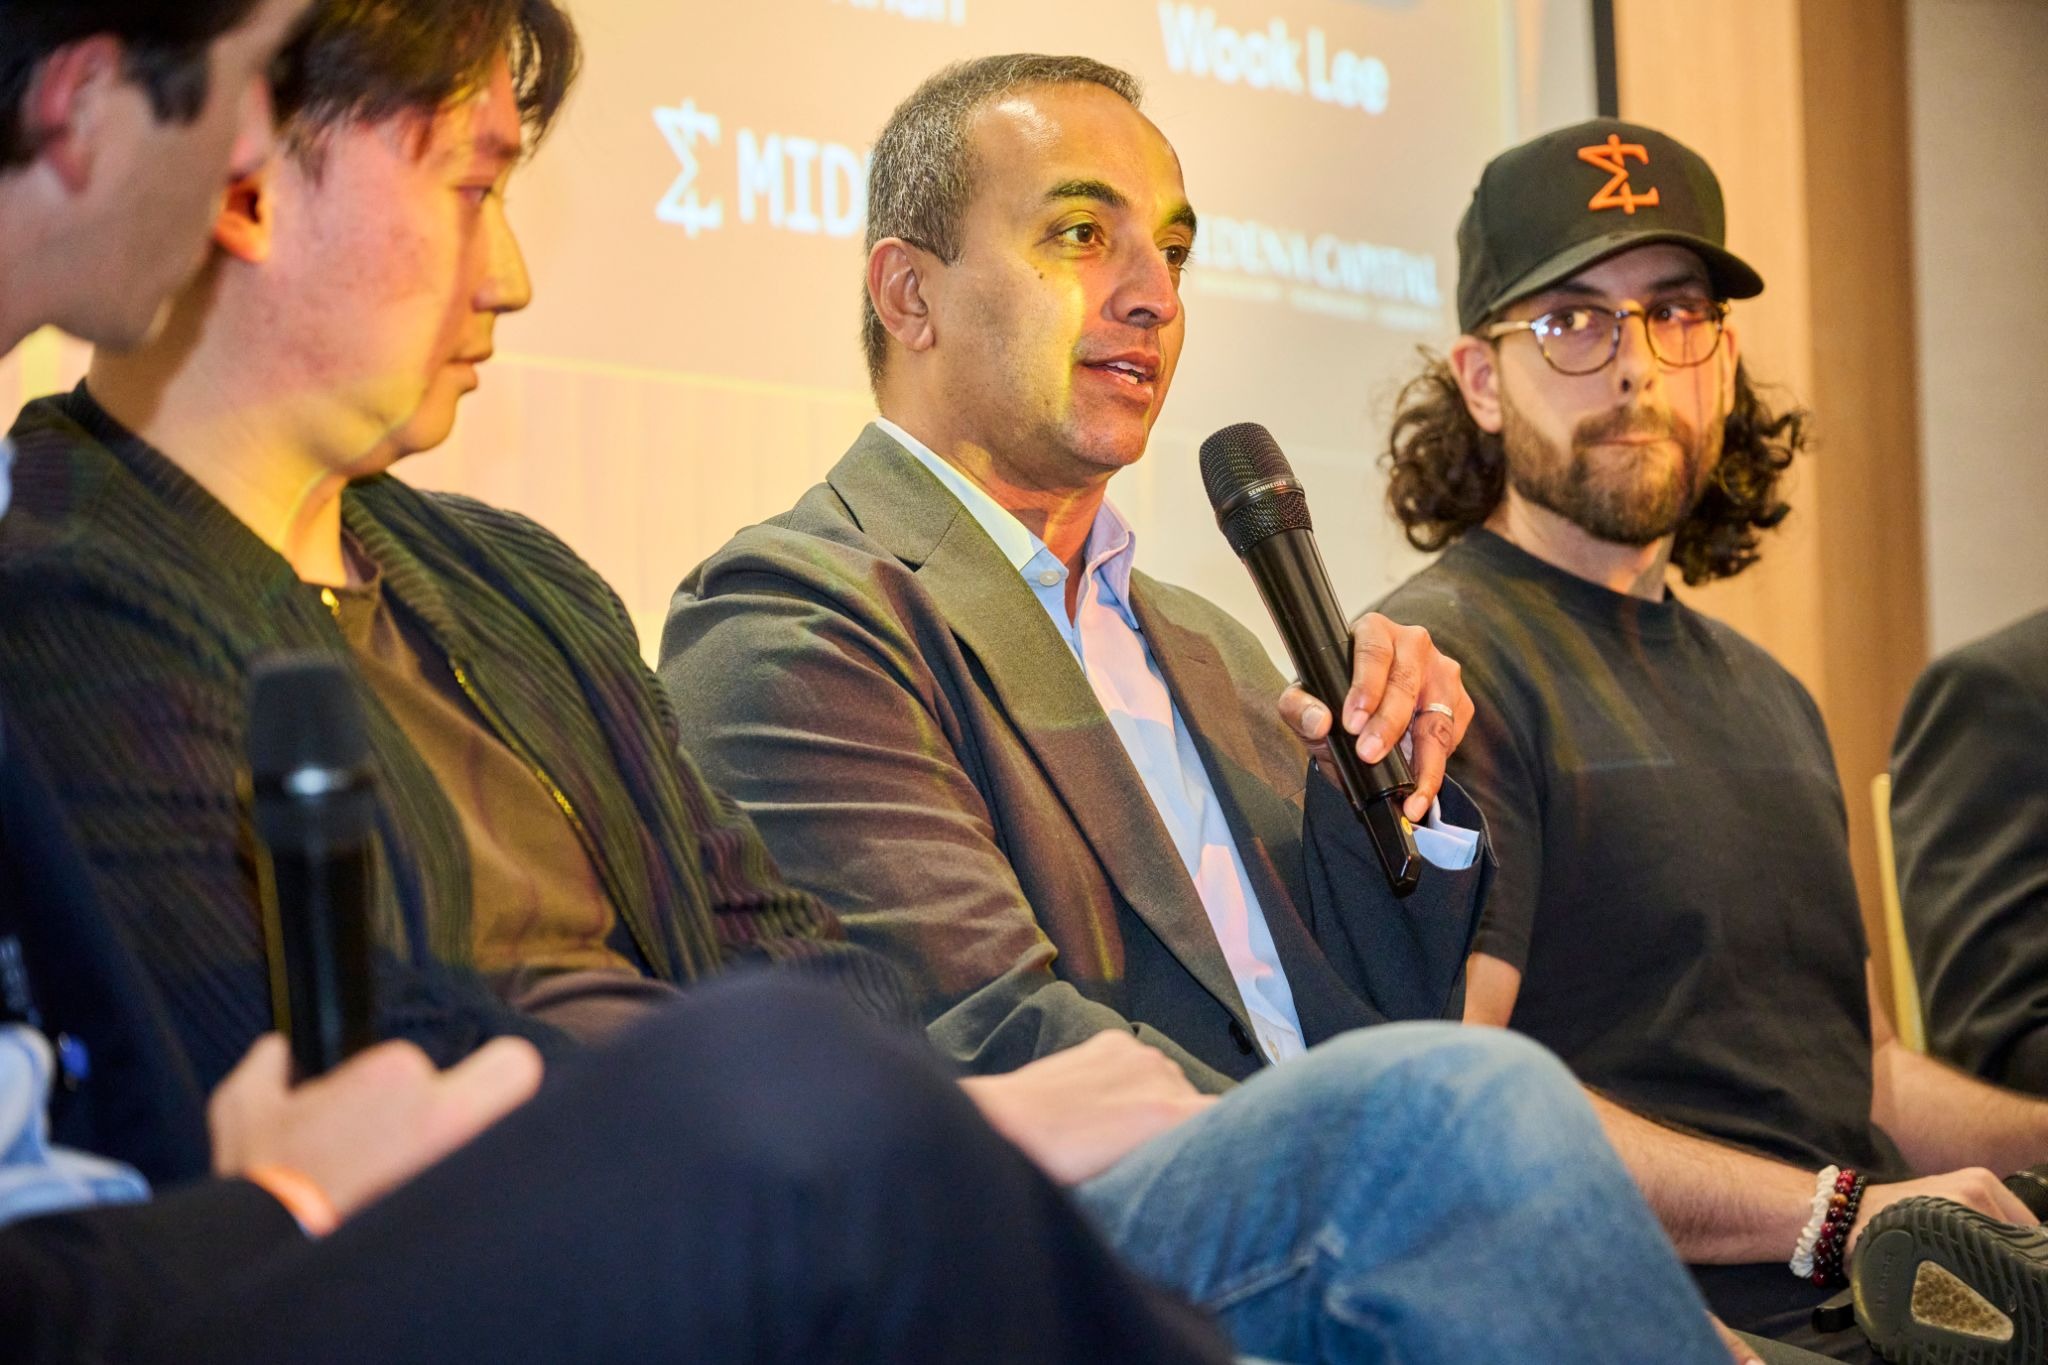
Haonan Li, co-founder and chief executive officer of the stablecoin FX network Codex, noted that utilization of stablecoins for settlements is expanding along trade corridors linking Latin America and sub-Saharan Africa with Asia, where purchasers dispatch capital to settle payments for manufactured merchandise traveling in the reverse direction.
“The manufactured goods flow from east to west and funds flow from west to east,” Li observed.
Related: SEC allows Franklin Templeton funds to invest in onchain money fund
Crypto treasuries face a liquidity test
Corporations evaluating crypto balance sheet models must possess capital they can lock up over extended periods without disrupting operational workflows, argued Ilya Podoynitsyn, co-founder and chief executive officer of FinHarbor, a CONNECT partner.
“If you don’t have that excess liquidity for doing that, you need to think very carefully before entering the market,” Podoynitsyn cautioned.
He advised against replicating another organization’s blueprint blindly without factoring in disparities regarding balance sheets, cash availability parameters, and risk appetites. Even seasoned corporate finance divisions may lack specialized understanding concerning decentralized liquidity frameworks and transaction validation protocols, he added.
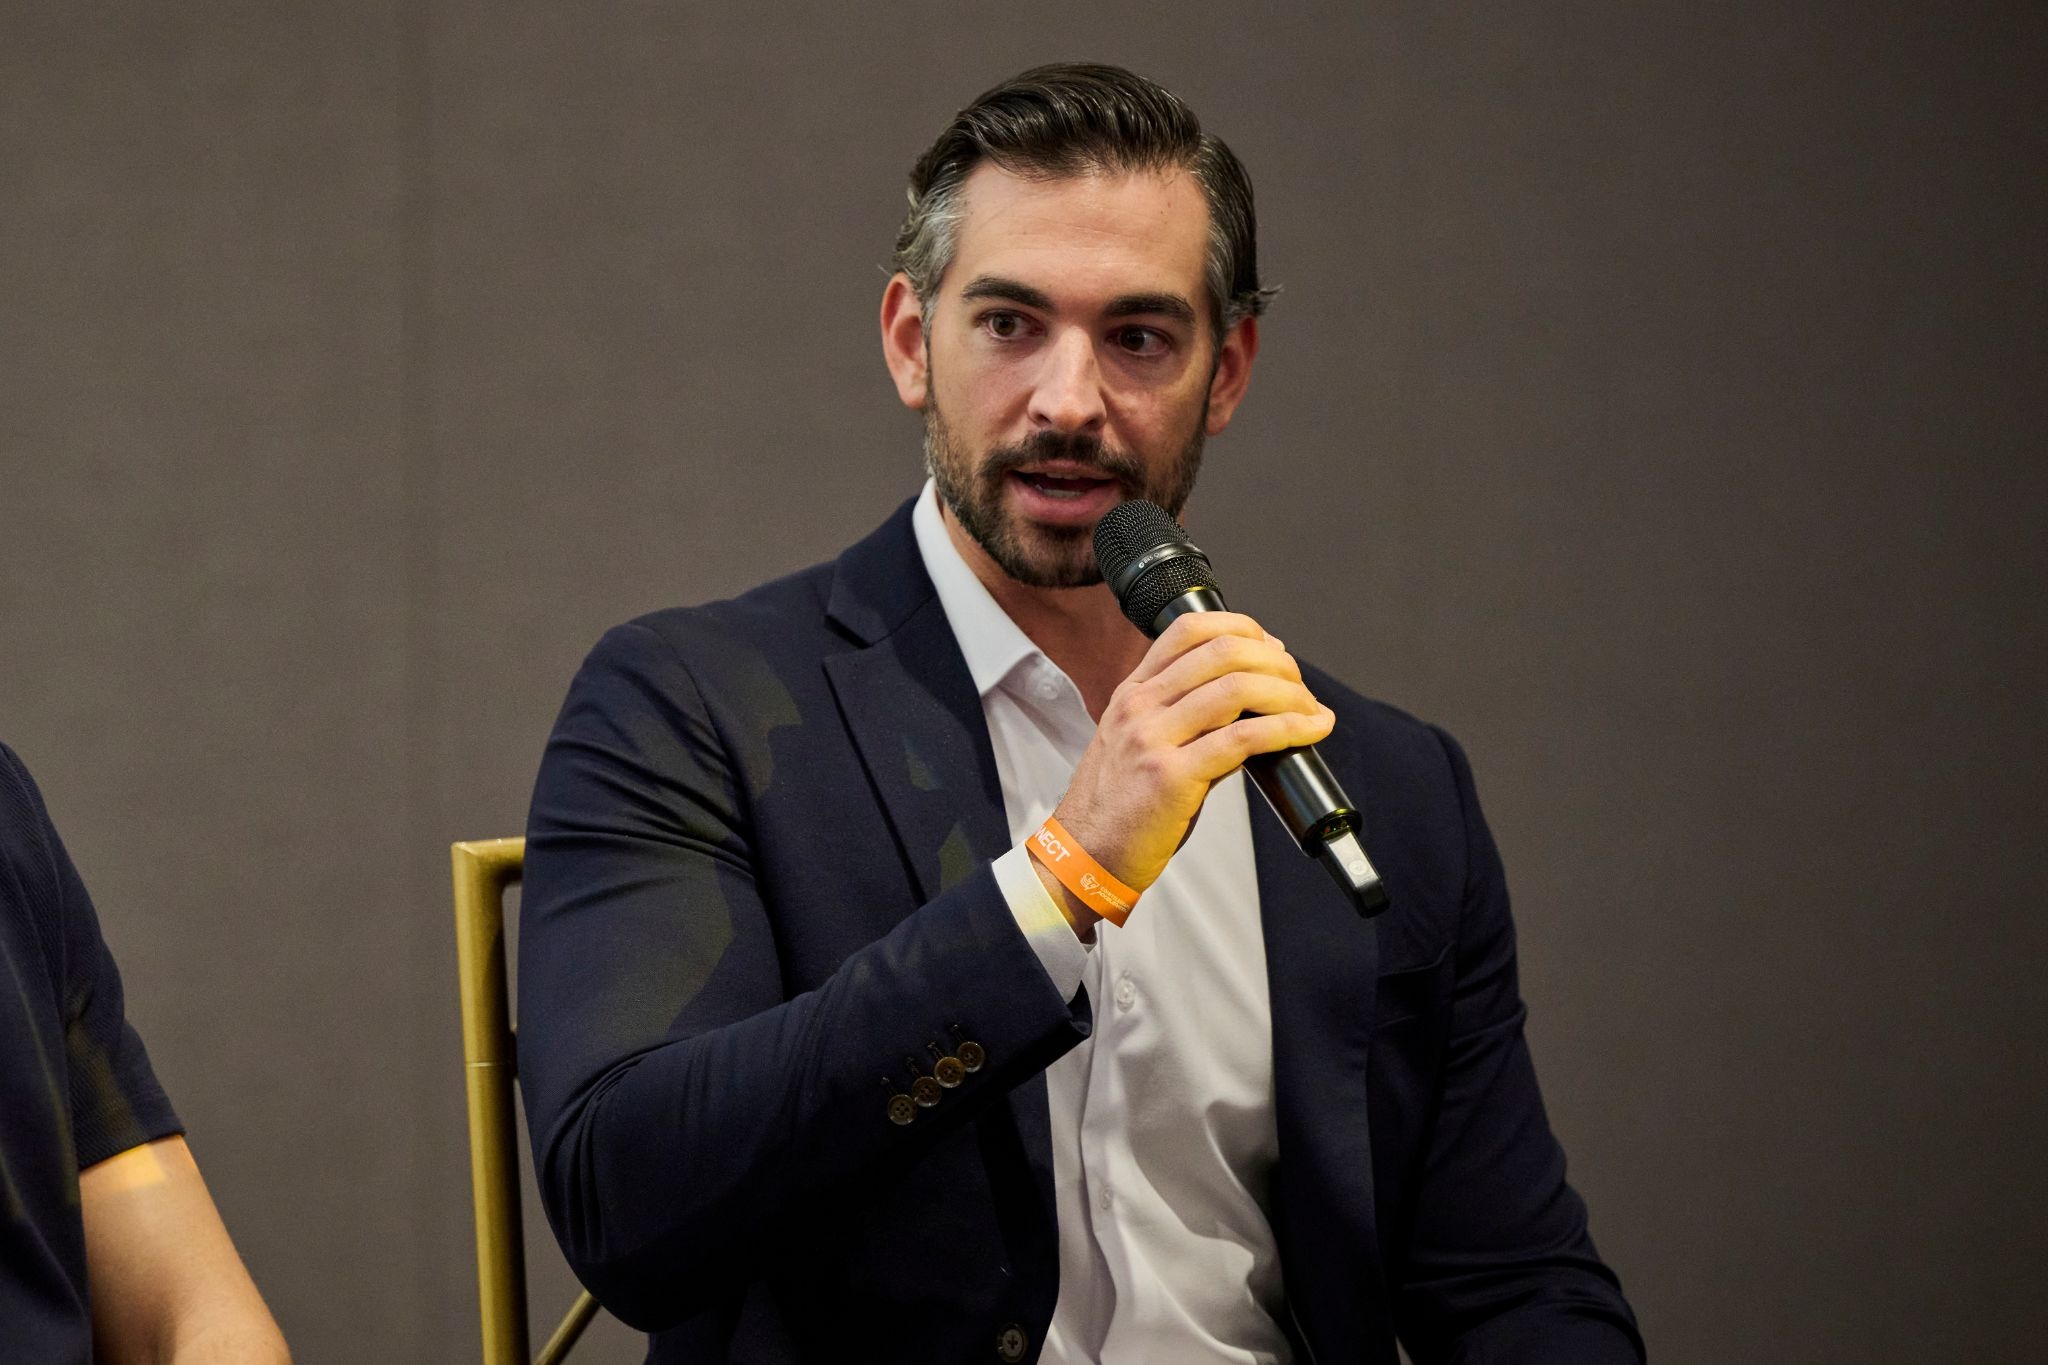
The discussion group also evaluated whether a publicly traded treasury enterprise holding unallocated funds ought to acquire additional digital assets or initiate equity buybacks when shares trade below net asset value.
Michael Camarda, chief development officer at the Ethereum treasury firm SharpLink, explained that executing share repurchases and acquiring extra Ether represent two distinct methods to elevate ETH reserves per share.
Deploying liquid funds to buy back stock divides existing Ether reserves among a reduced total share count, whereas acquiring more Ether directly expands corporate assets.
SharpLink’s institutional shareholders placed priority on ETH metrics per share, making buybacks more suitable for them, while retail participants tended to gravitate toward news regarding major Ether acquisitions, Camarda noted.
“They love headlines. They love numbers,” Camarda said regarding retail buyers.
SharpLink ultimately pursued both Ether acquisitions and equity buybacks to cater to each distinct investor segment, Camarda concluded.
Magazine: Bitcoin treasury firms can outperform BTC… but is the risk worth taking?
Cointelegraph is dedicated to impartial, open reporting. This piece of journalism was produced in alignment with Cointelegraph’s Editorial Policy and seeks to deliver precise and current details. Audience members are urged to verify details independently.
Originally published at https://cointelegraph.com/news/connect-recap-arthur-hayes-money-printing-wall-street-onchain?utm_source=rss_feed&utm_medium=rss&utm_campaign=rss_partner_inbound.