Updated Nov 20, 2026, 10:53 a.m. EST. Published Nov 20, 2026, 9:54 a.m. EST.
3 min read
AI could make alternative data cheaper and easier to access, eroding an advantage hedge funds once paid millions to secure.
Former Point72 executive Kirk McKeown sees a future where companies generate recurring revenue by selling their data.
Data could eventually be used to back financing deals, though privacy rules, ownership rights and valuation challenges remain major hurdles.
During his tenure leading market intelligence at Point72, the hedge fund established by Steve Cohen, Kirk McKeown allocated millions of dollars toward acquiring data designed to give portfolio managers an edge over the market.
Credit card records, consumer shopping habits, and other metrics rarely found on standard corporate balance sheets formed an integral part of the investigative pipeline. The objective was to identify corporate shifts long before they surfaced in financial earnings reports.
It was a capital-intensive operation. Acquiring the raw feeds presented initial obstacles, while extracting meaning demanded battalions of analysts, software engineers, and researchers.
McKeown, who spent upward of eight years managing Point72’s intelligence unit following a stint at Larry Robbins’ Glenview Capital, now maintains that the paradigm is primed for disruption, driven by forces extending well beyond mere cost reductions enabled by artificial intelligence.
He envisions an ecosystem where enterprises monetize their proprietary data generation, secure recurring cash flows, and potentially leverage those income streams to support future debt and equity structures.
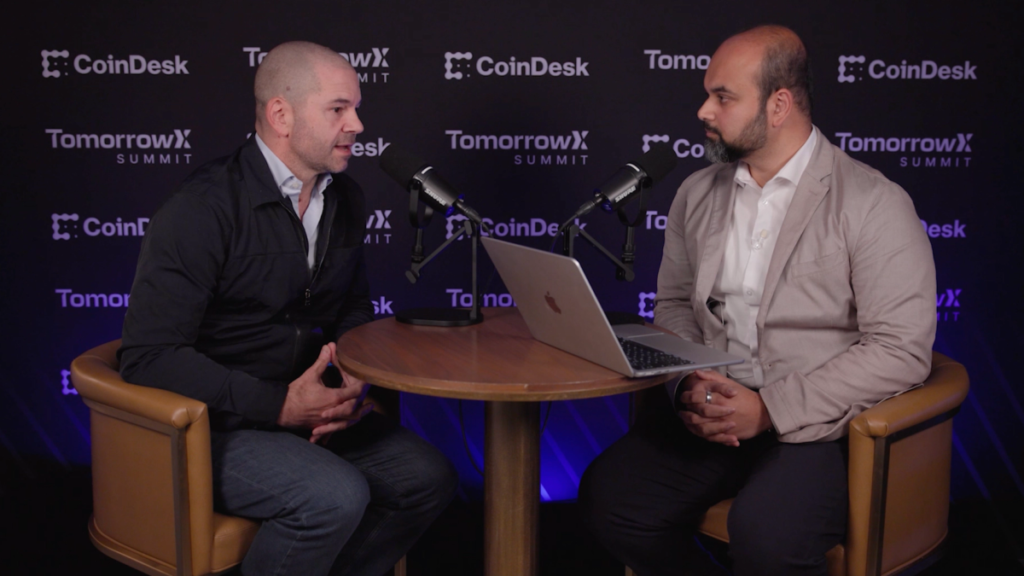
"There’s a new capital market forming, which is data structure," McKeown, currently CEO of alternative data platform Carbon Arc, stated during an interview with CoinDesk.
The price of an edge
Hedge fund managers rely on what the sector terms alternative data to gather intelligence on corporations independently of standard financial disclosures and regulatory filings. Such information is rarely classified, yet acquiring it requires substantial financial investment.
This exact friction point is what McKeown aims to fix through Carbon Arc. The enterprise aggregates transaction feeds from commercial entities, encompassing credit card activity, retail volume, and medical insurance claims, subsequently structuring them into formats optimized for investors and machine learning algorithms.
According to Carbon Arc, its repository houses roughly 600 distinct datasets. Rather than purchasing entire data archives, users deploy autonomous AI agents to query specific company metrics, compensating only for the precise information consumed. The underlying businesses providing the raw inputs obtain a proportional percentage of the generated revenue.
McKeown suggests that artificial intelligence can streamline this entire pipeline, empowering market participants to extract granular insights without purchasing and evaluating massive data pools in their entirety. Nevertheless, as broader segments of the investor community gain access to identical data points, traditional hedge funds face the distinct prospect of losing an informational moat that they previously funded at great expense.
"Alpha always moves," McKeown remarked.
He highlights credit card records, which gained traction within hedge fund strategies around 2012 and initially served as a proprietary source of edge before transforming into a standard component of mainstream investment research.
The competitive advantage, he contends, is shifting away from raw data access and toward the proficiency needed to formulate proper inquiries and interpret outputs correctly.
When data starts making money
McKeown’s longer-term vision extends far beyond traditional investment analysis. He maintains that commercial enterprises can convert the immense data volumes produced through routine payments, invoicing, and consumer interactions into reliable income streams.
That evolution could pave the way for credit facilities secured against prospective data sales, mirroring traditional income-generating financial assets. "Data is an asset," he noted. "It’s an economic earning asset today."
Nonetheless, substantial roadblocks persist. Information assets currently lack universally accepted valuation frameworks, while data privacy legislation, ownership protections, and compliance mandates complicate monetization strategies and collateral utilization.
McKeown asserts that establishing a fully realized market will require much clearer regulatory guidelines.
Even so, the ultimate ramifications for Wall Street could prove profound. As artificial intelligence democratizes information availability, hedge funds risk forfeiting the exclusive informational advantages they once secured at high costs. Simultaneously, operational businesses may uncover entirely new avenues to monetize the intelligence they naturally generate.
Read More: Coinbase CEO says AI agents will account for ‘99.9%’ of transactions within a decade
Originally published at https://www.coindesk.com/markets/2026/11/20/former-point72-head-of-proprietary-research-says-ai-could-turn-data-into-a-new-asset-class-for-wall-street.