Nov 20, 2026, 12:32 a.m. EST
3 min read
Summary
- PowerCompute directed the sale of about 267 bitcoin to repay nearly $22 million in loan principal, sharply reducing its secured debt without a margin call or forced liquidation.
- Despite the debt reduction, the bitcoin miner reported about $650,000 in cash at the end of September and warned that substantial doubt remained about its ability to continue operating.
- Management plans to refinance debt and sell more shares, potentially diluting investors whose holdings have already fallen sharply in value.
Bitcoin miner PowerCompute sold most of its bitcoin to get out of debt this fall, but its quarterly filing still says there is substantial doubt the company can keep going.
The Nasdaq-listed bitcoin miner had pledged 307 bitcoin to Arch Lending, which makes loans against crypto.
On Sept. 24, Arch sold about 267 of them to pay off nearly $22 million of principal and returned the remaining 40 or so, according to PowerCompute’s 10-Q.
“The sale was directed by PowerCompute. It reflected a change in their corporate strategy, not a market event. Their facility was a structured product with no margin calls and no liquidation triggers,” Himanshu Sahay, co-founder and chief revenue officer of Arch Lending, told CoinDesk.
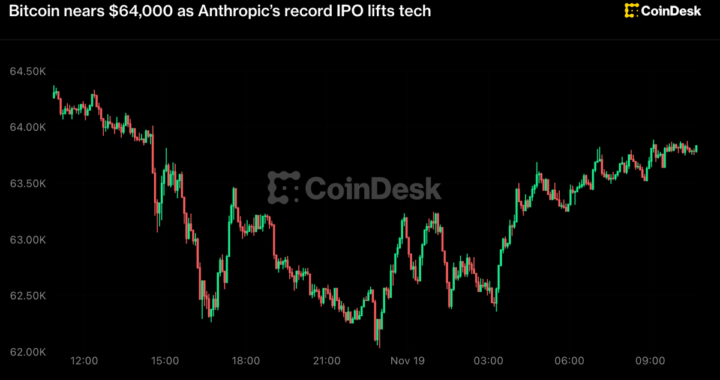
The sale cut PowerCompute’s secured debt from nearly $24 million to $1.25 million and left none of its bitcoin pledged. Those 267 coins would fetch about $17 million at bitcoin’s current price near $64,000, per CoinDesk data, less than the debt they cleared.
The cash is still the problem. The 10-Q, filed last week, shows about $650,000 in cash at the end of September and says “substantial doubt about the Company’s ability to continue as a going concern has not been alleviated.”
Management’s plan leans on refinancing some debt and selling more stock through an at-the-market program, which lets the company sell new shares gradually into the market and has about $71 million of capacity left.
The filing warns that further equity financings “may have a dilutive effect on shareholders.”
Those shareholders have already taken a beating. PowerCompute shares closed Thursday at about 40 cents, valuing the whole company at roughly $1 million, a fraction of what its bitcoin is worth.
On Tuesday, shareholders gave the board authority to carry out a reverse stock split of between 1-for-2 and 1-for-10, per an 8-K filing, four months after the company completed one in July.
That’s a tight spot for a company still running about 8,300 mining machines at hosted sites. It mined about 24 bitcoin in the third quarter, 36% more than a year earlier.
PowerCompute reported a quarterly profit of about $388,000, helped by a nearly $7 million gain from revaluing bitcoin held under its loan arrangement and partly offset by an approximately $4 million loss on the loan’s price-protection terms, per its third-quarter results.
In November, it paid about $1 million in cash for 600 new machines, which it expects to add about 10% to its computing power once they start running in December.
As such, Sahay shared that few of Arch’s borrowers settle the way PowerCompute did.
“Most borrowers still repay in cash, and more often than not they roll their loans over so they can keep borrowing. In some cases, settling with Bitcoin makes sense for a company’s balance sheet, depending on its cost basis and where the price is, but that’s the exception, not the norm,” he said.
“Our clients are long-term Bitcoin holders. They generally want to keep their Bitcoin, not use it to pay down a loan,” he added.
Bigger miners have been selling outright. MARA sold 13,597 bitcoin for $1.1 billion in six weeks and said it plans to sell more. By the end of October, PowerCompute held about 66 bitcoin, worth roughly $4 million at today’s price.
Read More: Bitcoin miner MARA sold 13,597 BTC for $1.1 billion in six weeks, plans to sell more
Originally published at https://www.coindesk.com/markets/2026/11/20/this-bitcoin-miner-sold-267-btc-to-clear-usd22-million-debt-it-still-may-not-survive.