JPMorgan moves more than $3 trillion through its Kinexys blockchain platform, and Citi Token Services handles billions daily in international transactions. Both stand out as prime examples of major financial institutions modernizing outdated architectures by integrating distributed ledgers for cross-border settlements; however, neither solution serves everyday retail banking customers.
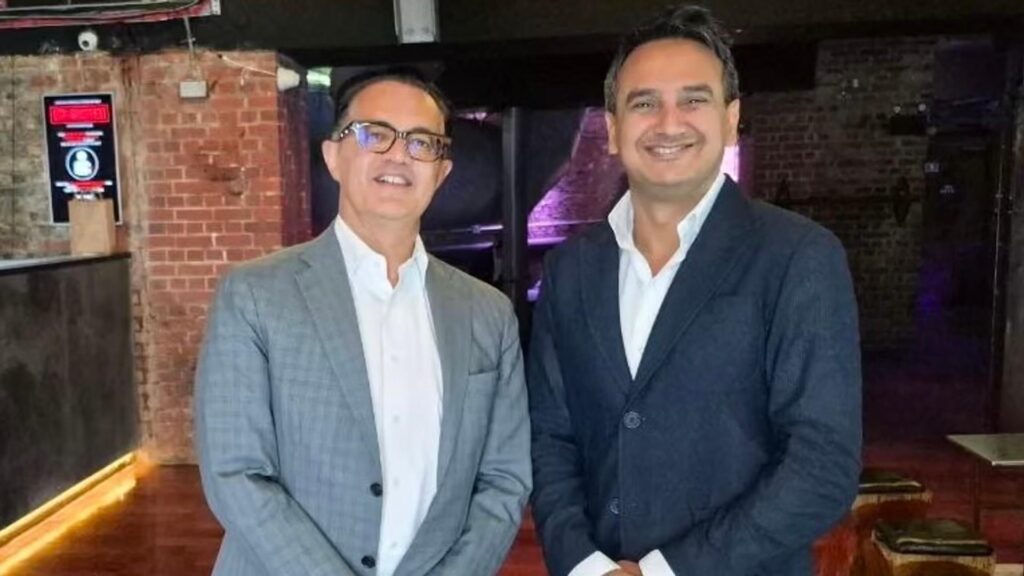
This discrepancy is completely intentional. According to Mintoo Bhandari, founder of Monument Bank—a UK challenger institution holding roughly $2.4 billion in assets—most digital tokens minted and deployed for funds transfers remain internal corporate initiatives.
He questions whether these efforts genuinely move the needle for the institution as a whole or for everyday users, concluding that they do not yet.
This captures the core division within current discussions surrounding tokenized finance. Traditional lenders are placing tokenized deposits and payment systems onto distributed networks, yet most initiatives stay locked inside permissioned environments or cater exclusively to institutional clients. Meanwhile, Monument Bank and privacy-centric distributed network Midnight are betting that regulated, interest-bearing customer accounts can eventually grant retail users access to tokenized investments and lending features without demanding any underlying knowledge of digital currencies.
Legacy Infrastructure
Bhandari noted that roughly 99% of global financial institutions claim to be completely digital because they offer mobile applications, while in reality, they remain shackled to foundational architectures dating back to the 1970s that they cannot easily bypass.
Jerald David, chief executive officer of Lynq Network, explained that institutional treasury departments must currently juggle three distinct systems to perform a single task. This includes a JPMorgan tokenized deposit for one counterparty, a compliant stablecoin for a second, and a traditional correspondent banking account for a third, moving funds for identical reasons across entirely fragmented frameworks.
He emphasized that clients simply cannot absorb the burden of separate liquidity pools locked within every single network they utilize, noting that fragmented idle capital spread across five distinct systems is five times less capital-efficient than idle funds consolidated in one location.
Unlike standard stablecoins, a tokenized deposit represents a direct claim against the issuing financial institution. Such an instrument can accrue interest, stay within the boundaries of conventional banking regulations, and potentially execute automated settlements against tokenized financial assets. The primary challenge is whether lenders can extend these advantages to consumers while simultaneously preserving privacy, regulatory compliance, and strict oversight regarding account ownership.
Interest-Bearing Deposits
Bhandari explained that unlike issuers of stablecoins, Monument holds an official banking charter that permits it to distribute interest on balances, with plans to introduce tokenized savings products capable of generating returns.
Fahmi Syed, president of the Midnight Foundation, pointed out that public distributed networks introduce an additional hurdle: financial institutions cannot risk exposing confidential client transaction histories or proprietary commercial partnerships.
Syed explained that once an organization builds a private blockchain, it faces the problem of communicating with external private ledgers, requiring bridges or alternative mechanisms that inevitably create data leaks. He noted that industry giants like JPMorgan and Citibank have already acknowledged this exact limitation.
While private bank-operated networks function effectively as internal ledgers, bridging them to outside systems without revealing sensitive data proves significantly more complex. According to Syed, Midnight leverages zero-knowledge proofs to allow institutions to independently verify that transactions or participants satisfy specific criteria without publishing the underlying personal records on-chain.
Consider a scenario where an investment fund receives repayment via stablecoins on a Saturday morning. Although the digital settlement clears successfully, the fund faces a major obstacle if it requires those funds to satisfy a margin call ahead of Monday market openings, because the prime broker’s treasury operates strictly during traditional banking hours and refuses digital assets. The required capital sits idle yet remains entirely unusable.
David described this as capital that exists but is severely dislocated, meaning it simply cannot be deployed where and when required.
Retail Tokenization
Monument announced intentions to tokenize up to £250 million ($335 million) worth of retail consumer deposits utilizing the Midnight protocol. These balances would continue generating interest, remain fully collateralized by Monument, and stay redeemable at parity in British pounds, backed by the Financial Services Compensation Scheme up to statutory limits.
Bhandari emphasized that no organization has successfully allowed retail participants to engage directly in tokenization until now. The architecture is explicitly engineered so that users never realize—nor need to understand—that underlying distributed ledger or crypto technology is involved. Instead, Bhandari noted, the overall user experience will mirror a standard pound sterling deposit that permits withdrawals at any time.
The extended objective is to grant those same retail clients seamless access to fractionalized private equity, structured investment products, and Lombard credit directly inside a compliant banking application, subject to requisite regulatory approvals.
Bhandari concluded that if the model succeeds, his organization intends to license the underlying technology stack to third-party lenders via an entity named Monument Technology. The ultimate test for the industry is not whether institutions can successfully tokenize currency, as they already possess that capability, but rather whether they can deliver genuine utility to everyday consumers without compromising the privacy, legal safeguards, and institutional trust that fundamentally differentiate a bank account from a digital token.
Originally published at https://www.coindesk.com/business/2026/09/15/why-wall-street-giants-build-tokenization-money-for-institutions-not-regular-consumers.